
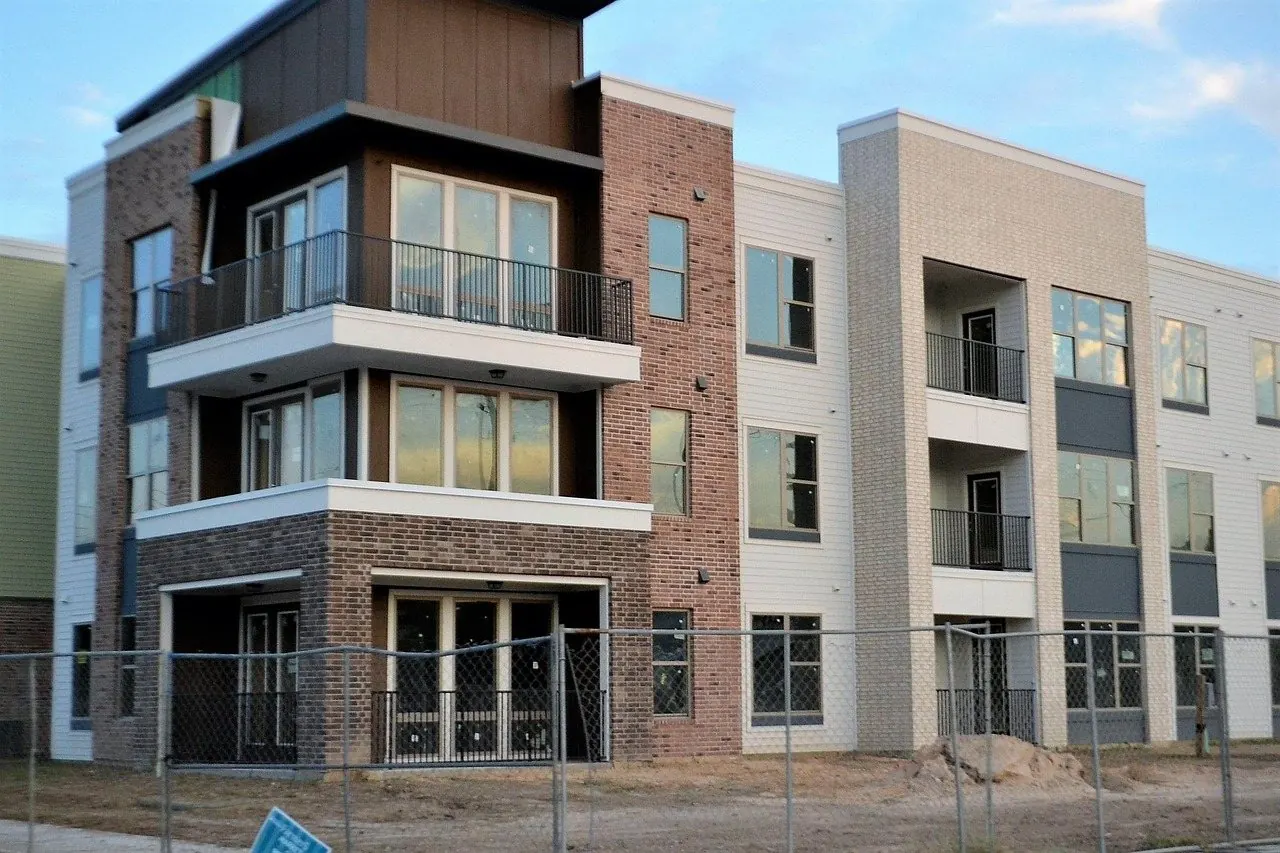
Most lenders don’t find mixed-use straightforward. The ones who will engage have specific appetites that vary by use combination, geography, deal size and borrower profile.
Mixed-Use: What It Means to Lenders
Developers define mixed-use broadly, and rightly so. Residential above retail. Live-work units. A hotel component alongside private apartments. Office space and leisure within the same building. The definition shifts depending on the scheme, and that flexibility is part of the appeal.
Lenders see it differently. Each use class is a separate risk category, assessed with different methodologies, different market data, and different assumptions about who buys or occupies the completed asset. A lender on a mixed-use scheme is underwriting two or more assets at once, and the interaction between those uses adds complexity a single-use development doesn’t have.
The first consequence: fewer lenders will engage than it appears. Most mainstream lenders avoid mixed-use altogether. Specialist lenders will engage, but their appetite varies significantly. A lender comfortable with residential above retail on a high street may have no appetite at all for a hotel-and-residential scheme or a live-work conversion in a secondary location.
Knowing which lenders are active for your specific use combination is where deal preparation starts.
“A lender on a mixed-use scheme is underwriting two or more assets at once, and often would rather not.”
The Valuation Problem
Valuation is the central friction point on mixed-use development finance, and it needs more attention at the appraisal stage than most developers give it.
On a straightforward residential scheme, the RICS valuer appointed by the lender works from comparable sales data. On a mixed-use scheme, that methodology covers only part of the building.
The commercial element requires a yield-based income capitalisation approach, which means the valuer has to consider tenant covenant strength, lease length and structure, void risk, and the restrictions on future occupation that sit within the use class.
Related: What Matters More Than Rates in Development Finance?
| Valuation factor | Residential element | Commercial element |
|---|---|---|
| Methodology | Comparable sales | Yield-based income capitalisation |
| Market data used | Recent comparable transactions | Rental evidence, yield benchmarks, covenant quality |
| Key variables | Location, size, specification | Void risk, lease length, tenant covenant, use class restrictions |
| Degree of subjectivity | Lower: anchored to comparable evidence | Higher: multiple judgement calls required |
| Conservative valuer impact | Moderate: comparable evidence limits downside | Greater: conservative yield and void assumptions compound |
Two methodologies, applied to two parts of the same building, then reconciled into a single security figure. The judgements are more subjective than on a single-use scheme, and lenders’ panel valuers will be more conservative than on residential.
Planning position intersects with this directly. A scheme with full planning and clear use class permissions is a very different proposition from one where the commercial floorspace ratios are ambiguous or the permitted uses are broad. The valuer has to make assumptions where the planning is unclear, and conservative assumptions have a cost.
| Before you approach a lender Stress-test your GDV against a conservative valuation, meaning a cautious yield on the commercial element, a void assumption, and a conservative covenant. If the deal only works at your own numbers, the margin is thinner than the appraisal suggests. On mixed-use schemes, the gap between a developer’s GDV and the lender’s panel valuation tends to be wider than on residential. Build that in before you go to market. |
How Lenders Assess a Mixed-Use Development Deal
Lenders assessing mixed-use development finance are underwriting the security, the exit, and the borrower’s ability to deliver, in that order, across more variables than a single-use scheme.
| Assessment area | What the lender is assessing | What it means for preparation |
|---|---|---|
| Security and planning | Clean title across all use elements. Planning conditions confirmed for the commercial component: operating hours, permitted uses, service access. | Identify title complexity before engaging lenders. Mixed-use and conversion schemes often carry layered histories. Resolve or disclose early. Queries at legal stage cost time you don't have. |
| The appraisal | Residential and commercial GDVs assessed separately using different market data. LTC and LTGDV ratios on mixed-use often sit below pure residential levels, reflecting higher perceived risk. | Model at mixed-use gearing levels. Developers who assume residential leverage and find out the terms at credit stage have a structuring problem they could have avoided. |
| Exit strategy | Exit audience for mixed-use is narrower, typically investors, which introduces yield requirements and tenant covenant strength. A void commercial element at practical completion significantly narrows refinance options. | Plan the exit scenario where the commercial element underperforms. A pre-agreed development exit bridge may be the answer, but it needs to be in the funding structure from day one. |
| Developer experience | Track record on residential doesn't automatically satisfy requirements on mixed-use. Comparable use combinations, commercial leasing knowledge, and understanding of the mixed-use exit market all factor in. | If stepping into mixed-use from a residential background, the quality of your advisory team and the clarity of your plan carry more weight than they would on a purely residential scheme. |
Where Mixed-Use Development Finance Deals Go Wrong
Most mixed-use deals that don’t complete cleanly, or complete late and over-cost, come down to a handful of recurring problems. None of them is unpredictable in hindsight.
Approaching the wrong lender
The mixed-use lending market is more fragmented than most developers realise. Lenders have specific appetites for use combination, geography, LTV, and deal complexity.
Broadcasting to several lenders without knowing their current position wastes time a time-sensitive deal doesn’t have.
A GDV that won’t survive the valuation
If the deal only works at the developer’s own GDV number, it will be fragile the moment the lender instructs their panel valuer. The commercial element introduces variables that are difficult to control: void assumptions, yield expectations, covenant strength. Valuers will take a cautious view of all of them.
Vague exit planning
An exit strategy built on assumptions without evidence will either fail at credit or be priced for the risk. The exit scenario where the commercial element is underperforming at completion needs to be planned in as much detail as the primary exit. Lenders will ask. The answer needs to be specific.
Title and planning issues emerging mid-legal
Mixed-use and conversion schemes often carry layered histories: use class changes that weren’t formally documented, access arrangements that worked in practice but were never tied into the title, Section 106 obligations that weren’t fully understood at appraisal. Each generates a legal enquiry. Each enquiry adds time.
Related: The Legal Side of Development Finance: Every Developer Must Know
Underestimating the information required
Underwriting a mixed-use scheme requires more than single-use development: commercial lease documentation, tenant covenant information, planning history across different use classes, valuation evidence from both residential and commercial comparable markets.
An incomplete pack at lender approach generates queries, which generate delays.
Bridging vs Development Finance for Mixed-Use Schemes
The right funding structure depends on project stage and what comes next. The table covers the four scenarios that come up most often.
| Scenario | Appropriate product | Key considerations |
|---|---|---|
| Ground-up mixed-use construction with a staged build programme | Development finance facility | Staged drawdowns against build progress, monitored by an IMS. Typically structured around a construction programme of 18 months or more. |
| Acquisition of existing mixed-use building for conversion or refurbishment | Bridging loan | Where scope doesn't justify a full development facility and speed of execution matters. Bridge to acquisition, then transition to a development facility once planning is confirmed. |
| Build complete, residential selling, commercial void or on a short lease | Development exit bridge | Repays the development facility at or near practical completion. Buys time to secure a commercial tenant without forcing a discounted sale or a default. |
| Sequential: bridge to acquire, transition to development finance | Bridge → Development finance | This sequence must be designed as a whole from the outset. Structuring the second facility after the first is in place significantly narrows available options and limits lender appetite. |
# Preparation Is the Differentiator
The mixed-use deals that move through quickly are the ones where the preparation matched the complexity of the scheme. That means:
- GDV stress-tested against a conservative valuation before lender approach
- Exit strategy mapped across multiple scenarios, including the one where the commercial element doesn’t perform as planned at completion
- Title and planning reviewed for complexity before legal is instructed
- Lender selection made on the basis of specific appetite for the use combination, geography, and deal size
- The application presented the way lenders are used to receiving it, structured around their assessment criteria
The legal work, the monitoring surveyor appointment and the valuation surface problems that were already there. The deals that slow down or unravel at these stages almost always contain issues that were visible earlier, had anyone been looking.
At Fundingwise, we stay involved from the first conversation through to final drawdown. We know where mixed-use deals face friction, which lenders have appetite for which use combinations, and what a complete application looks like for this part of the market. Done properly, that preparation changes how a deal ends.
Related: The Development Finance Process: From Application to Drawdown
Need Development Finance for a Mixed-Use Scheme?
Fundingwise works with developers and property professionals across the UK, structuring debt for mixed-use, refurbishment, conversion, and ground-up residential schemes.
If you’re early in a mixed-use project and want to know where your deal will face scrutiny, talk to us.
Book a free consultation | Call us: 020 4571 6186
Got a scheme to fund?
Property finance, in your inbox
Property finance insights from the Fundingwise team.
We'll email you a link to confirm. See our privacy policy for how we use your details.