
Build it
Build it
Development finance
Ground-up, conversion and part-built schemes, from site purchase to exit.
See all →
Development finance
Which limit sets your loan, loan to cost or loan to GDV, and how much day one equity that leaves you.
Build to Rent development
Underwritten on stabilised yield and DSCR, not sales rate.
Mezzanine and stretched senior
The gap between senior LTC and what you can fund, and the blended cost.
Heavy refurbishment and conversion
Where refurbishment stops being a bridge: structure, change of use, drawdowns.
Part-built and rescue finance
Valuing an unfinished asset when the contractor has gone.
Bridge it
Bridge it
Bridging finance
Short-term debt where the deadline, the asset or the exit will not wait.
See all →
Purchase bridge
Completing before the money is in place: chain breaks, tight deadlines, unmortgageable stock.
Development exit finance
Off development debt at a lower rate, to buy sales time and release equity.
Auction finance
A 28-day clock, and what must be in place before the hammer falls.
Pre-planning and planning gain
Lending against current value with planning upside.
Below market value purchase
Day-one lending against open market value rather than price.
Second charge and capital raising
Raising against existing assets, and first-charge consent.
Light refurbishment finance
Bridge plus refurb tranche, and where the development boundary sits.
Also structuredBridge to let and refinance
Hold it
Hold it
Mortgages and term finance
Long-term debt against income, once the asset is built, let or trading.
See all →
Buy to let mortgages
ICR stress testing, limited company against personal, portfolio rules.
HMO mortgages
A higher cover test, licensing, and two valuations, with some lenders lending on the lower.
Commercial term, investment
Tenant covenant and lease term, and why DSCR sets the loan.
Commercial term, owner-occupier
Trading accounts and EBITDA rather than rent roll.
Portfolio refinance
Cross-collateralisation, and one facility against individual loans.
Stabilisation and term refinance
The income test replacing the GDV test, and the letting void before term debt engages.
Co-living and PBSA
An operational asset valued on income, and the operator covenant.
Run it
Run it
Business finance
Funding the business behind the property, secured on the ledger, the equipment or the covenant.
See all →
How we work
Case studies
Articles
Tools
Development finance calculator
Size the facility against site cost, build cost and GDV.
Development exit calculator
Refinance the development facility and release equity at PC.
Bridging finance calculator
What a bridge costs, and what reaches you on day one.
Refurbishment finance calculator
Fund the purchase and 100% of the works, with interest rolled to exit.
BTL rental cover calculator
The rent a buy to let must achieve to clear a lender's cover test.
Commercial mortgage calculator
What a commercial property's income will support, and what it costs.
About
Enquire now
Build it › Build to Rent development
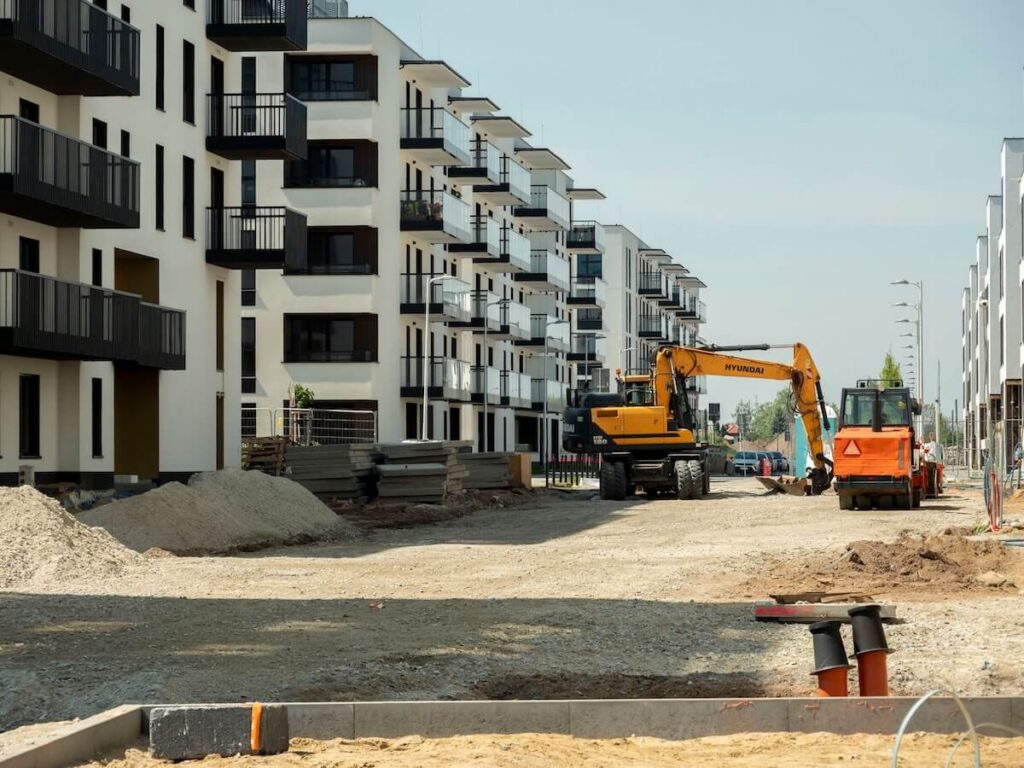
A for-sale scheme is tested against sales rate and gross development value. A build to rent scheme is tested against the rent it will produce once let and stabilised, income that does not exist on the day you borrow.
That moves the test you hit first from GDV to debt service coverage: whether the net rent covers the term debt, typically 1.25 to 1.5 times. A scheme that prices well on a sales appraisal can fail that test outright.
The other thing that moves is the timetable. A BTR programme runs longer than the build, because it includes letting up and stabilisation, and most term lenders want to see occupancy of around 90% before they will commit to the refinance. The letting period has to be built into the finance structure.
Size the development facility before the income test is applied to it.
The exit tested before you build
The term lender's DSCR test is what the development facility has to hand over to. We run that test at appraisal, on stressed assumptions. At practical completion it is too late.
Rental evidence
Comparable lettings, in the same postcode, at the same specification. A rent roll assumed off a sales appraisal is the most common reason a BTR case stalls in credit.
Stabilisation funded
There is a period between practical completion and stabilised occupancy where the asset produces some income and carries full debt. That gap needs funding, and it belongs in the facility, not your working capital.
Operating costs in the model from the start
Management, voids, bad debt and maintenance all sit between gross rent and the income a lender will count. A lender will not accept cover worked out on gross rent.
Which lenders play here
Development lenders with a BTR desk, then a separate universe of institutional and specialist term lenders for the exit. The two conversations are best held at the same time, because the term lender's requirements set the shape of the development facility rather than the other way round.
1.25-1.5x
Typical cover on net rent
25-35%
Gross rent to running costs
90%
Occupancy term lenders want
1.25x
Lowest published lender cover
Indicative, and not an offer. What a lender offers depends on the scheme, the borrower and a full valuation.
What to have ready
Bring these and we can tell you where you stand.
A lender will ask for each one. Have them early and the answer comes faster.
✓A costed appraisal with a rent roll, not just a sales schedule
✓Comparable lettings evidence for the specification you are building
✓Operating cost assumptions: management, voids, bad debt, maintenance
✓Programme including the letting and stabilisation period
✓Any term lender interest already secured, and on what conditions
✓Track record, in development and in operating or managing let stock
Related
Worth reading on this
Article
How to Fund a Build to Rent Development Finance Scheme
Article
Mezzanine Finance: Bridging the Equity Gap on Your Next Development
Article
Free Development Finance Calculator & Loan Appraisal Guide
Next
Related in this pillar.
Development finance
Which limit sets your loan, loan to cost or loan to GDV, and how much day one equity that leaves you.
Mezzanine and stretched senior
The gap between senior LTC and what you can fund, and the blended cost.
Heavy refurbishment and conversion
Where refurbishment stops being a bridge: structure, change of use, drawdowns.
Common questions
The questions this product raises.
How is build to rent finance different from build to sell?
A build to sell scheme is tested on what the units sell for. A build to rent scheme is tested on whether the net rent, once let, covers the term debt, typically 1.25 to 1.5 times, and that rent does not exist on the day you borrow.
What occupancy will a term lender want before it refinances?
Around 90%, in most cases. Until then the scheme carries the full debt on part of the income, so fund the letting period inside the development facility.
Can the rental cover test use the gross rent?
No. Management, voids, bad debt and maintenance come off first, typically 25 to 35% of gross rent, and the lender tests cover on what is left. Put those costs in the model from the first appraisal.
When should I speak to the term lender?
At the same time as the development lender. The term lender's requirements shape the development facility, so its cover test belongs in the appraisal, before you build.
Bring us the detail.
Send what you have. We will tell you what is fundable and what needs work before anyone approaches a lender.
Property finance, in your inbox
Property finance insights from the Fundingwise team.
We'll email you a link to confirm. See our privacy policy for how we use your details.
Specialist property finance for developers who want the numbers to survive underwriting.
020 4571 6186LinkedIn
Fundingwise Limited is not authorised or regulated by the Financial Conduct Authority, and arranges unregulated finance only. That means lending secured against commercial property, or against residential property that is not, and will not be, occupied by the borrower or an immediate family member as a main residence. We do not advise on or arrange regulated mortgage contracts or regulated bridging loans. Because this finance is unregulated, FCA conduct rules and access to the Financial Ombudsman Service do not apply. Fundingwise Limited is registered in England and Wales, company number 13750788.