
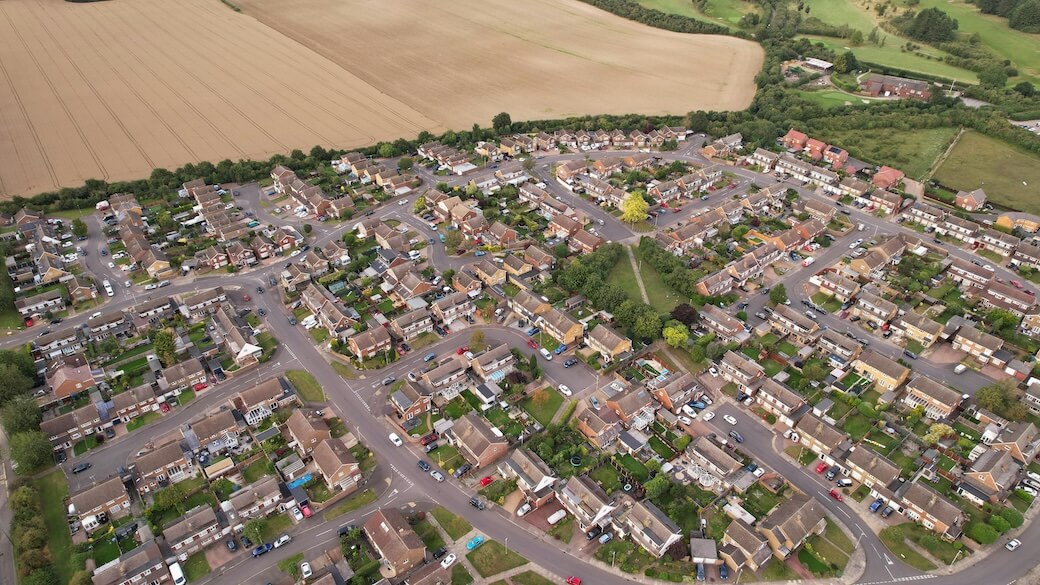
For developers, knowing what drives those cycles matters for timing projects, securing finance, and spotting opportunities when larger players pull back.
Below: what shapes UK property markets, how sales and supply interact, and where SME developers fit.
What drives property transaction volumes
UK property sales don’t follow a steady pattern. Transaction volumes swing between roughly 900,000 and 1.4 million completions a year, depending on economic conditions.
Key drivers of transaction volumes:
1. Mortgage rates and affordability
When mortgage rates fall, affordability improves and buyers return. When rates rise, affordability tightens and transactions drop. Broadly:
- Sub-4% mortgage rates typically drive higher transaction volumes (1.2 to 1.4 million a year)
- Above 5% rates suppress activity, particularly among first-time buyers (volumes drop to 1 to 1.1 million)
Small rate movements matter too. A 0.5% drop can bring back thousands of buyers who were waiting for affordability to improve.
2. Real wage growth and employment
Property markets follow employment and wages. When real wages grow (wages outpace inflation), buyer confidence improves and volumes rise. When real wages stagnate or fall, buyers delay and volumes drop.
First-time buyers, the most sensitive to affordability, feel this most.
3. Housing stock availability
Volumes also depend on supply. When listings are high, buyers have more choice and competition softens. When stock is tight, bidding wars return and prices rise, but fewer transactions complete because buyers can’t find suitable properties.
Markets with plenty of stock tend to see higher volumes and slower price growth. Markets with little stock see lower volumes and stronger price inflation.
4. Buyer confidence and economic sentiment
Even when affordability is good, confidence matters. Uncertainty about jobs, inflation or politics makes buyers delay. Confidence returns when the outlook stabilises, even if conditions aren’t perfect.
That’s why property markets often lag economic recovery by 6 to 12 months: buyers wait for certainty before committing.
The regional picture in early 2025 was uneven. Homes sold subject to contract rose in Q1 2025 against Q1 2024 in every English region, led by the East Midlands at 13.9% and the North West at 12.9%, while Northern Ireland fell 1.6% (TwentyEA data). Zoopla Research's January 2025 ranking of price growth prospects put much of Scotland, Northern Ireland and the North of England near the top, and much of the South East and South West near the bottom.
New build supply: chronic undersupply and structural constraints
The UK consistently builds fewer homes than it needs. Government targets (typically 300,000 homes a year) are rarely met, with delivery between 180,000 and 240,000 depending on the cycle.
Why supply lags demand:
1. Planning delays and complexity
UK planning is slow, adversarial and short of resources. Even straightforward applications take 6 to 12 months. Complex schemes can take years. Local authorities lack the capacity to process applications quickly, and political opposition to new housing adds more hurdles.
Planning risk is one of the biggest constraints on supply. Projects that can’t get planning don’t get built.
2. Build cost volatility
Construction costs move with material prices, labour availability and the wider economy. When build costs spike (inflation, supply chain disruption, wage pressure), marginal schemes stop working and supply drops.
Developers on tight margins are most exposed. Well-capitalised builders can absorb cost increases; smaller operators often can’t.
3. Labour shortages
Construction has persistent shortages of skilled labour, particularly in bricklaying, carpentry and electrical work. That slows builds and raises costs, limiting how many homes can be delivered even when demand is there.
4. Land availability and cost
Viable development land is finite, particularly in high-demand areas. As land prices rise, fewer schemes stack up. Developers either pay more (less profit) or build elsewhere (less supply where demand is highest).
5. Section 106 and infrastructure costs
S106 obligations and infrastructure requirements add significant upfront costs. For SME builders on smaller sites, these can make schemes unviable, particularly when councils demand disproportionate contributions.
“SME developers once built 40%+ of new UK homes. Today it is closer to 10 to 15%.”
SME developers: squeezed but essential
Small and medium-sized developers once accounted for 40%+ of all new homes built in the UK. That share has collapsed over the past two decades and now sits closer to 10 to 15%.
Why SME builders have lost market share:
1. Planning processes favour scale
Large strategic sites dominate local plans, leaving fewer opportunities for smaller builders. Planning departments prioritise major applications (100+ units) over smaller schemes, which means delay and uncertainty for SME developers.
2. Upfront costs and cash flow constraints
S106 contributions, infrastructure bonds and pre-commencement costs hit SME developers harder than volume builders. Large developers can spread these costs across multiple sites; smaller operators working on 5 to 20 unit schemes can’t.
3. Access to development finance
Volume builders have established banking relationships and cheap capital. SME developers rely on specialist lenders with higher rates and lower LTVs, so marginal schemes are harder to finance.
When credit tightens (rising rates, cautious lenders), SME builders are hit hardest.
4. Land acquisition challenges
SME developers often compete with volume builders for land but can’t pay the same prices, because their build efficiency is lower and their finance costs higher. That pushes them toward harder, less desirable sites, with more risk and weaker viability.
When SME developers gain opportunities
Despite these constraints, SME developers do well in specific conditions:
Market uncertainty: When confidence drops or costs spike, volume builders pause land buying to protect margins. SME builders can move faster, buying overlooked smaller sites and completing 12 to 18 month build programmes while larger competitors wait.
Niche markets: Volume builders focus on large strategic sites near cities and ignore small infill plots (5 to 15 units), brownfield regeneration and regional towns. SME developers do well in these niches, delivering housing that suits the location and that larger builders can’t justify economically.
Supportive policy: Planning reforms that speed up smaller schemes (permitted development, simpler processes for sub-50 units) cut planning risk and make smaller sites more viable.
Stable financing conditions: When mortgage rates fall and buyers return, SME developers with shorter build programmes can complete and sell faster than volume builders, before conditions shift.
Regional variation: not all markets move together
UK property markets are highly regional, and national averages hide a lot of local variation:
Typically stronger markets:
- Northern England, Scotland, Northern Ireland: lower prices, stronger affordability, consistent demand
- Regional cities with economic growth (Manchester, Leeds, Edinburgh, Bristol)
- Areas with employment growth outpacing housing supply
Typically weaker markets:
- London and South East: affordability ceilings, oversupply in some segments, slower transaction volumes
- Rural areas without economic drivers
- Markets heavily dependent on single industries in decline
For SME developers, regional dynamics matter. Build in the wrong market, however good the project, and you get slow sales, cash flow problems and refinancing risk.
How to position for market cycles
Developers who understand the cycle can time projects to it:
During high-activity periods (low rates, strong sales):
- Competition for land increases
- Build costs rise due to labour/material demand
- Sales are faster but margins compress due to land cost inflation
- Finance is easier to access but terms may be less competitive due to demand
During low-activity periods (high rates, slow sales):
- Land prices soften as competition drops
- Build costs stabilise or fall as demand for labour/materials decreases
- Sales are slower but profit margins can improve (cheaper land)
- Finance is harder to access but lenders compete for quality schemes
The developers who do best buy land in a downturn and build and sell into the upturn.
Need development finance for your next project?
Fundingwise works with SME developers across the UK, structuring development finance for refurbishment, conversion and ground-up residential schemes. We know the regional markets, help position projects for lender approval, and secure funding at every point in the cycle.
Send us the scheme and we’ll set out your funding options.
Got a scheme to fund?
Property finance, in your inbox
Property finance insights from the Fundingwise team.
We'll email you a link to confirm. See our privacy policy for how we use your details.