
The Challenges
Flood Risk Complexity
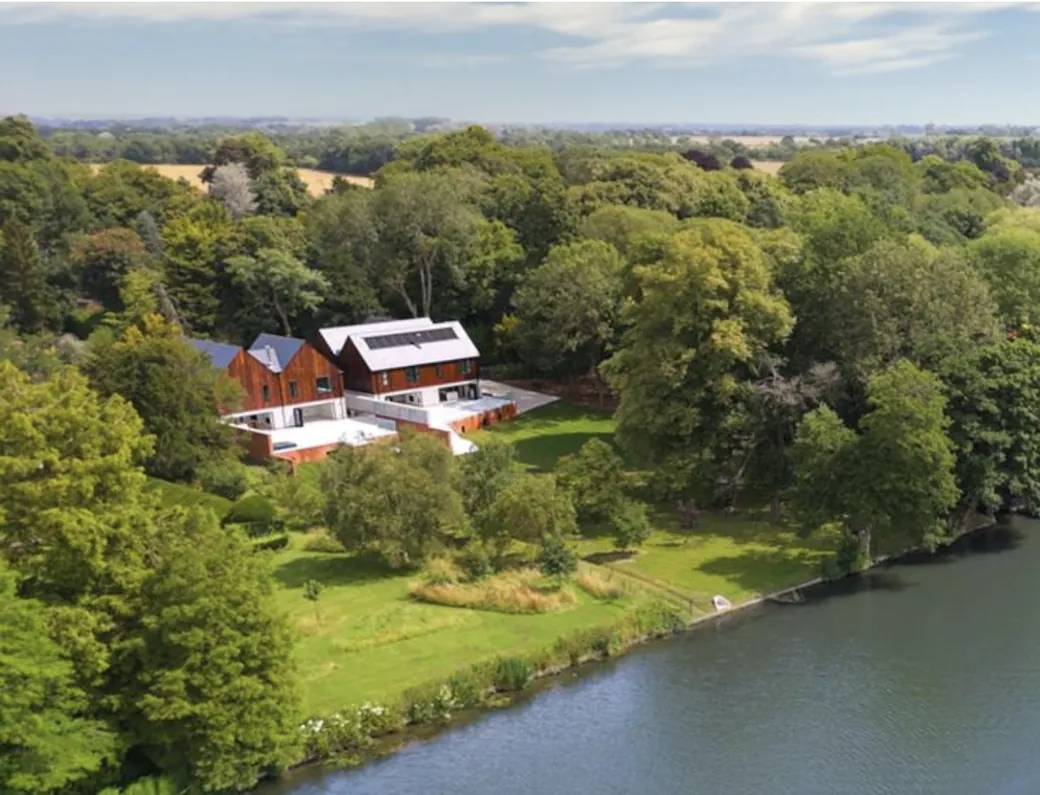
Most of the title sits in Flood Zone 3, and the mapping shows the properties in Flood Zone 2. There were mitigation measures, including raised structures and a Flood Risk Assessment confirming a Zone 1 classification, but insurers still relied on the standard mapping. Without acceptable insurance, the lender could decline.
Undischarged Pre-Occupation Conditions
Planning conditions on lighting and drainage were still undischarged. Most lenders require full discharge before completion, so the deal risked delay or failure.
Subordinate Debt Structure
A separately contracted loan was in place, and the client would not redeem or formally subordinate it. Most lenders treat that as a red flag, and it could have stopped the deal in legal due diligence.
The Solution
Fundingwise dealt with each issue before going to market:
- Made sure the client took out specialist insurance aligned with the Flood Risk Assessment, which met the lender’s requirements before valuation and legal review.
- Identified the undischarged planning conditions in early due diligence and placed the deal with a lender that accepted a condition subsequent structure, which removed the completion risk.
- Brought in the lender’s legal team before valuation to agree the approach on the separately contracted loan, so it did not cause problems late in legals.
- Structured the refinance to repay the primary lender and keep the client’s wider funding in place.
The Result
The deal completed on the client’s terms. The client can now focus on selling the homes without a loan expiry approaching.
- £3.1m facility completed
- 14-month extension to the sales period
- Flood risk, planning and debt structure issues resolved before completion
Ready to talk?
Property finance, in your inbox
Property finance insights from the Fundingwise team.
We'll email you a link to confirm. See our privacy policy for how we use your details.